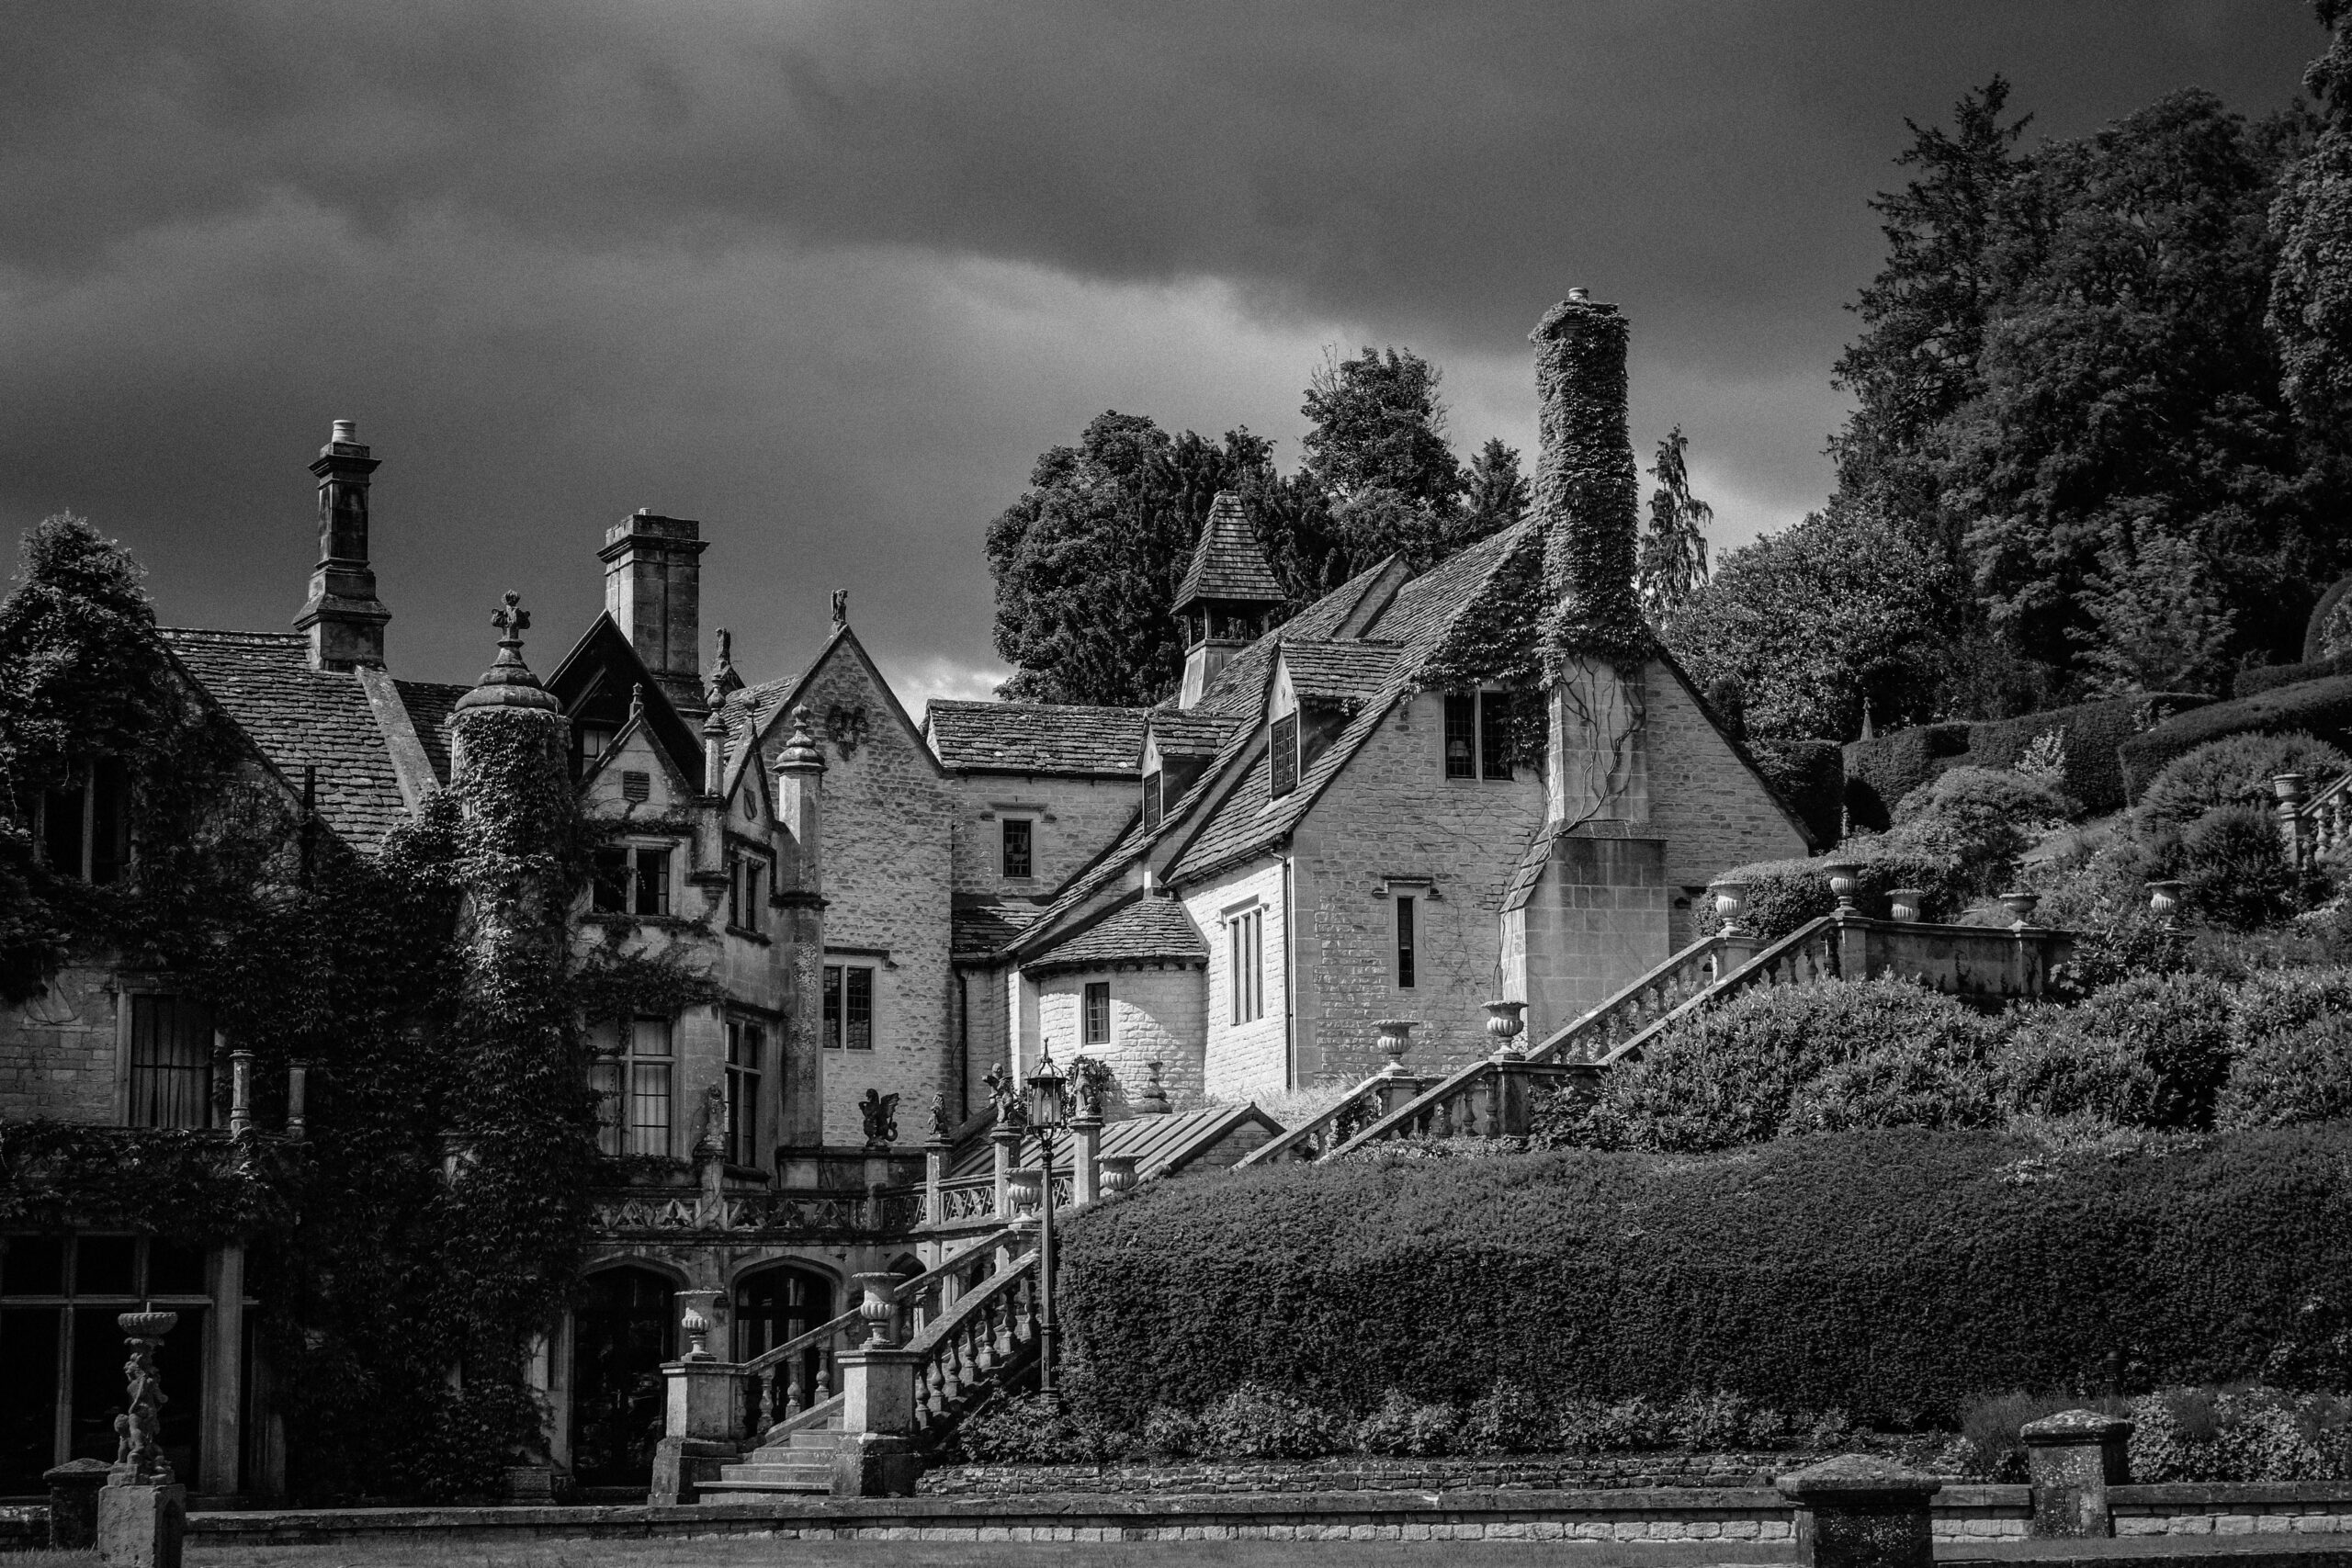
A 100-bedroom country estate hotel featuring extensive conference suites, leisure facilities, and food & beverage outlets undertook a phased £1.85m refurbishment. The programme included modernising guest bedrooms, upgrading 19 meeting and event suites, and enhancing the hotel’s swimming pool and wellness areas.
While the hotel operates with an internal CFO managing day-to-day finance, property refurbishment projects present complex tax challenges that often go beyond standard management accounting. Main contractor invoices typically arrive as composite, single-line items (“Fit-out works: £450,000”), which risks qualifying tax relief being mischaracterised as non-qualifying building repairs or structural expenditure.
The Challenge
- Opaque Contractor Cost Summaries: High-level valuation certificates obscured the underlying technical assets eligible for capital deductions.
- Separating Structures from Plant: Distinguishing between standard structural repairs (under Structures and Buildings Allowances at 3% per year) and high-value plant, machinery, and integral features eligible for immediate relief.
- Cash Flow Timing: The owners required maximum upfront corporation tax deductions to offset operational profits and fund subsequent refurbishment phases.
Detailed Review
- Unbundling Integral Features (Special Rate Pool): Extracted hidden electrical and lighting systems, space and water heating installations, cold water infrastructure, and ventilation/AC units across all 19 conference rooms and 100 guest rooms.
- Specialist Hotel & Leisure Plant (Main Pool): Identified qualifying operational assets within the health club and spa, including pool filtration systems, thermal suite plant, acoustic treatments, emergency lighting, and bespoke sanitary ware.
- Optimising Tax Relief Mechanisms: Leveraged the Annual Investment Allowance (AIA) to secure 100% immediate relief against taxable profits.
Financial Benefit
- Total Qualifying Allowances Identified: £1.24m in upfront plant, machinery, and integral features, plus an additional £180k qualifying for SBA.
- Direct Cash Tax Saved: Over £310,000 in corporation tax liabilities sheltered across the project period.
- Balance Sheet Impact: Maintained full tax compliance with HMRC, strengthened lender reporting covenants, and preserved operating liquidity to reinvest into the estate’s ongoing commercial growth.
Introductory Meeting
With over 30 years of combined experience, our digitally-enhanced finance function provides restaurant and hospitality entrepreneurs with financial clarity and specialist advice to navigate past obstacles, identify opportunities and grow with confidence.
To arrange an introductory meeting,
or for a quote, please complete the below form.